Buying a Home With Friends or Family: Conversations to Have First
Buying a Home With Friends or Family: Conversations to Have First
By The Rhonda Roberts Group at Keller Williams Collective
Quick answer: Before buying a home with friends or family, agree on how you’ll use shared spaces, split expenses, handle maintenance, make decisions, and manage a future move or sale. Put the financial and ownership terms in writing with help from a Kentucky real estate attorney, and talk with a lender about each borrower’s responsibilities before you start shopping.
Buying a home together can be appealing. Maybe you and a sibling want a place of your own, you’re considering a multigenerational household, or you and a close friend are exploring homeownership in Louisville.
But getting along over dinner is different from sharing a mortgage, a kitchen, and an unexpected repair bill.
Before you fall in love with a house, have these conversations. A little clarity now can help protect both your investment and your relationship.
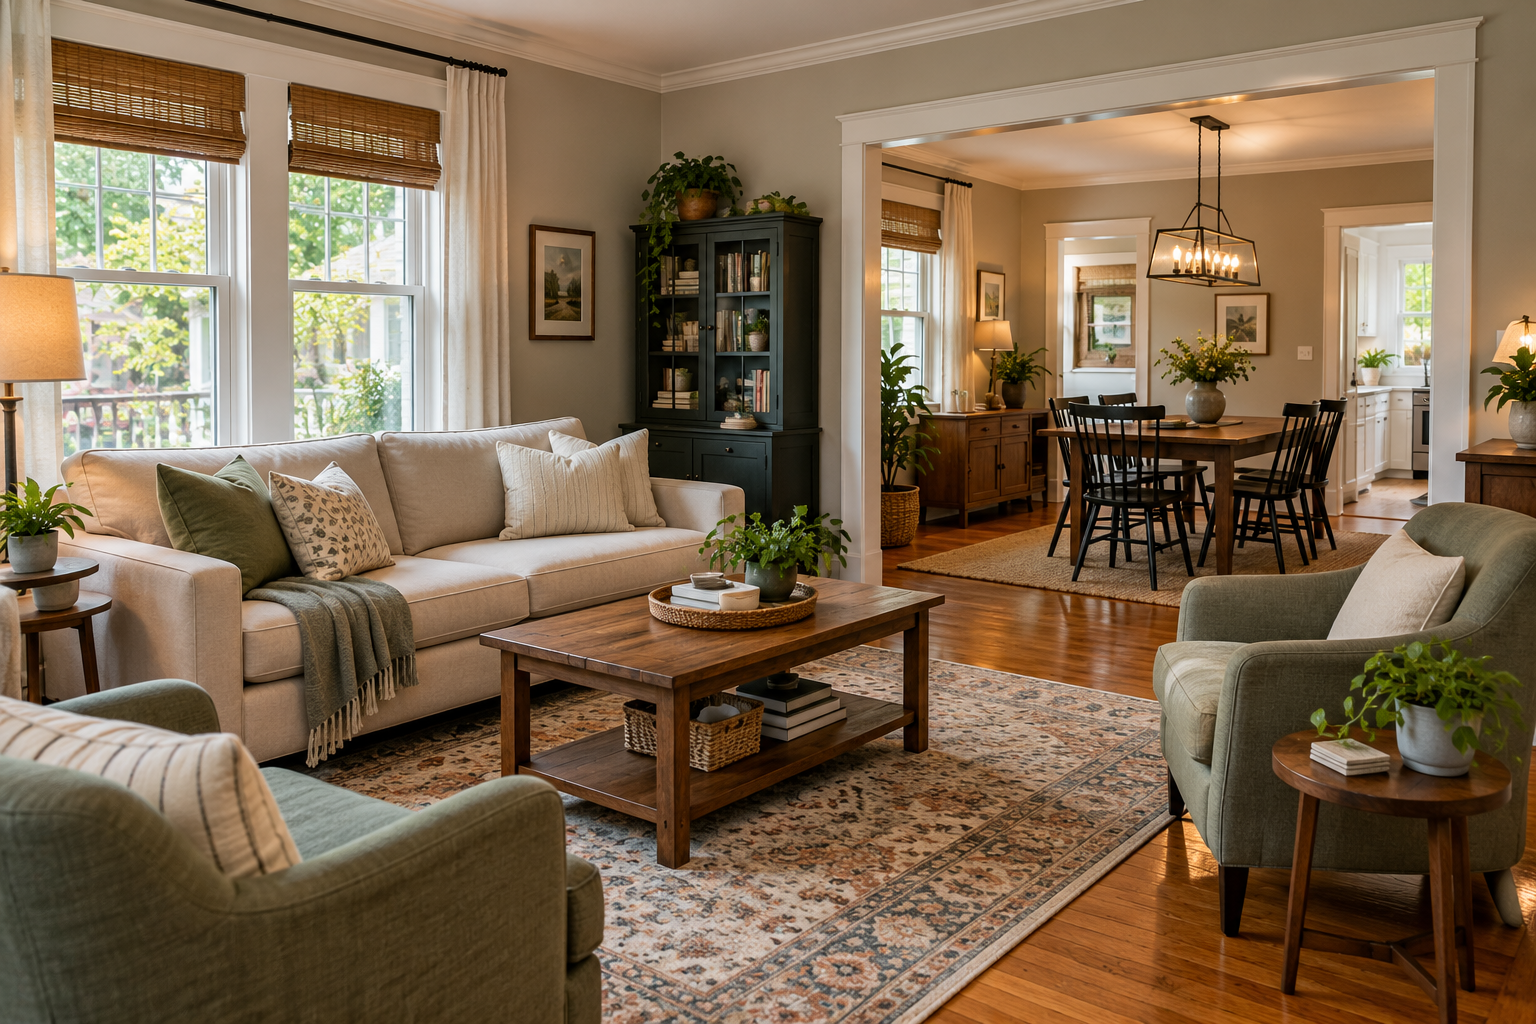
1. How will we use shared spaces?
An open floor plan might look beautiful during a showing. Will it still work when one person takes video calls from the dining table while another cooks lunch?
Talk through an ordinary weekday and weekend, including:
- Private space: Who gets each bedroom, bathroom, office, or storage area?
- Common areas: How will you share the kitchen, living room, laundry, garage, and yard?
- Daily routines: What are everyone’s expectations for cleaning, quiet hours, and thermostat settings?
- Guests and pets: How will you handle overnight visitors, extended family stays, and pet responsibilities?
- Parking: Where will each person park, and what happens when guests visit?
If one person gets a larger bedroom or a private bathroom, discuss whether that changes their share of household expenses. Keep that conversation separate from the legal ownership percentages you establish with your attorney.
House-hunting tip: Bring everyone’s must-have list to the first conversation with your Realtor. A floor plan that supports privacy can matter just as much as square footage.
2. How will we split the down payment and monthly expenses?
“We’ll split everything” sounds simple until you define everything.
Discuss the down payment, closing costs, moving expenses, mortgage payments, property taxes, homeowners insurance, utilities, and any HOA dues. Decide how you’ll track contributions and what happens if someone pays more upfront.
Use this table to start your shared budget:
| Expense | What to decide before buying |
|---|---|
| Down payment and closing costs | How much does each person contribute, and how is it documented? |
| Mortgage, taxes, and insurance | What does each person pay, when is it due, and who confirms payment? |
| Utilities and internet | Will you divide costs equally or use another agreed method? |
| Household supplies and cleaning | Which purchases are shared, and which stay personal? |
| Repairs and replacement costs | How much will you regularly set aside in a reserve? |
| Improvements | Who approves the work, pays for it, and keeps the records? |
Build your budget around a payment everyone can comfortably manage, including savings for repairs and personal goals.
Understand the mortgage obligation: A private agreement to split payments does not limit each co-borrower’s responsibility to the lender. The Consumer Financial Protection Bureau explains that co-borrowers can each be responsible for the full mortgage obligation. Ask your lender to explain this before applying.
Also decide what happens if someone loses income or misses their agreed contribution. Who covers the shortfall, how is it recorded, and when must you revisit the arrangement?
3. Who handles maintenance—and who pays for it?
One person may enjoy yardwork. Another may prefer hiring a lawn service. Neither preference has to be a problem if you agree before moving in.
Make a plan for routine chores, seasonal upkeep, and larger repairs. Assign responsibility for scheduling service as well as paying the bill.
Ask each other:
- Who handles mowing, gutters, filters, and routine cleaning?
- Which projects can we do ourselves, and when will we hire a professional?
- What spending amount requires everyone’s approval?
- Who can authorize an emergency repair if the others are unavailable?
- Will someone’s labor earn reimbursement or another credit, and how will that be documented?
For example, agree ahead of time on how you would handle a leaking water heater. You don’t want an urgent repair delayed while everyone debates who should call the plumber.
4. How will we make decisions and resolve disagreements?
Homeownership involves decisions that go beyond paint colors. Discuss who can approve renovations, changes to shared spaces, new occupants, or a proposed rental arrangement.
Choose a regular time to review bills, upcoming maintenance, and household concerns. A short monthly check-in can keep small frustrations from becoming bigger disputes.
Ask an attorney to help establish a process for decisions when you cannot agree, including whether mediation belongs in your written agreement.
5. What happens if someone wants to move out or sell?
Your plans may align today and change later. A job relocation, new relationship, growing household, or financial setback could affect how long someone wants to stay.
Discuss these questions before making an offer:
- How long does each person expect to own the home?
- How much notice should someone give before leaving?
- Will the remaining owners have an opportunity to buy that person’s share?
- How will you determine the property’s value and calculate a buyout?
- How will you account for unequal contributions, improvements, selling costs, or a loss?
- What happens if a buyout or refinance is not possible?
- What happens if an owner dies or becomes unable to manage their affairs?
Moving out or transferring an ownership interest does not automatically remove someone from the mortgage. Discuss any proposed exit with the lender and attorney, including what would be required to release a borrower. Don’t build your plan around an assumption that refinancing will be available later.
6. What should Louisville-area buyers consider?
When buying a home with friends or family in Louisville or surrounding counties, evaluate the property against everyone’s daily needs.
Compare commutes from the specific address, parking, bedroom placement, stairs, bathroom access, and room for working from home. If you’re considering Jefferson, Oldham, Bullitt, Shelby, or Spencer County, compare the actual property’s costs and location rather than assuming every home in a county will fit the same budget or lifestyle.
If your plan depends on a separate living area, basement bedroom, added kitchen, or future rental, verify the permitted use, required approvals, and any deed or HOA restrictions before committing. A separate entrance alone does not establish that a space can be used as an independent dwelling.
During the inspection period, discuss the home’s condition and likely upkeep together. Everyone should understand the responsibilities they’re considering.
Do we need a written agreement when buying together?
A written agreement can help everyone remember—and plan around—the same expectations. The CFPB encourages buyers purchasing with someone other than a spouse to consider legal help documenting responsibilities and future options.
A Kentucky real estate attorney can advise on ownership structure, title, contributions, decision-making, buyouts, and estate considerations. Your lender can explain financing requirements, and a tax professional can address questions about deductions or tax treatment for your situation.
Your Realtor helps connect those conversations to the home search: finding properties that fit your shared priorities and guiding you through the purchase process.
Your checklist before shopping together
- Agree on private spaces, shared areas, guests, pets, and routines.
- Create a budget for upfront costs, monthly bills, and repair savings.
- Meet with a lender to understand financing and borrower obligations.
- Decide who handles maintenance, payments, and recordkeeping.
- Discuss your exit plan and get legal help documenting the arrangement.
- Give your Realtor a shared list of priorities and deal breakers.
Thinking about buying a home together in Louisville?
The right home should support how everyone plans to live. If you’re considering buying with friends or family, our team is here to help you sort through your priorities and explore homes in Louisville and the surrounding counties.
The Rhonda Roberts Group at Keller Williams Collective
Connect with our team to discuss your homebuying plans and start your Louisville-area home search.
This article provides general information. Consult a Kentucky real estate attorney, lender, and tax professional for guidance specific to your purchase.
Recent Posts
GET MORE INFORMATION